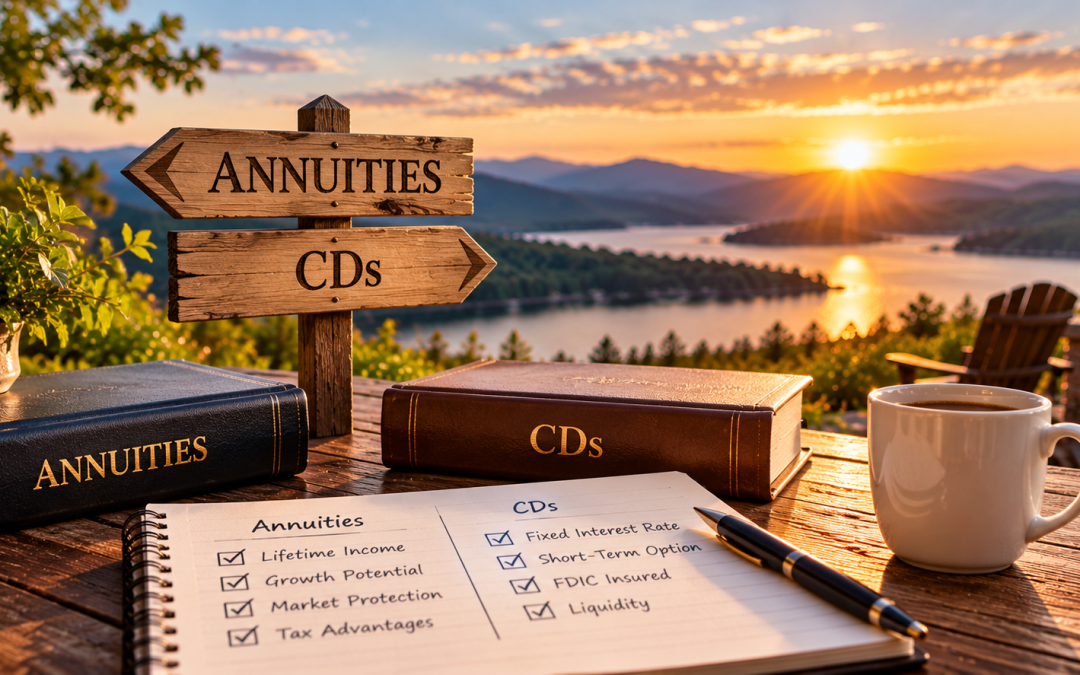
When comparing financial products that may offer stated interest rates or other guarantees, two options often enter the conversation: certificates of deposit and fixed annuities.
Although they can share certain characteristics, they are very different financial products.
Understanding those differences can help consumers ask more informed questions.
What Is a Certificate of Deposit?
A certificate of deposit, or CD, is a deposit product offered by a bank or eligible credit union.
CDs generally provide a stated interest rate for a specified term.
Eligible deposits at FDIC-insured banks receive federal deposit insurance protection within applicable ownership categories and limits. Eligible credit union deposits may have separate NCUA insurance.
Early withdrawals can result in penalties.
What Is a Fixed Annuity?
A fixed annuity is an insurance contract issued by an insurance company.
Depending on the contract, it may provide interest accumulation subject to specified guarantees, and it may offer future income options.
Certain fixed annuities guarantee an interest rate for a defined period.
Others have rates that may change at renewal, subject to contractual minimums.
A Key Difference: Insurance Protection
Bank CDs and insurance annuities are not protected in the same manner.
Annuities are not FDIC-insured deposits.
Annuity guarantees depend on the issuing insurance company’s claims-paying ability.
Some state guaranty association protections may apply to qualifying insurance contracts, subject to state-specific rules and coverage limits.
These protections should not be treated as equivalent to federal bank deposit insurance.
Liquidity and Withdrawal Restrictions
Both products may have costs associated with early withdrawals.
For CDs, the consequences generally follow the financial institution’s deposit agreement.
For deferred annuities, withdrawals may involve a surrender charge schedule, market value adjustment, tax consequences, or effects on certain benefits.
The availability of penalty-free withdrawals varies by annuity contract.
Taxes and Income Options
Interest earned on a traditional bank CD is generally subject to federal income taxation as it accrues, unless held through a tax-advantaged arrangement.
Earnings in many nonqualified deferred annuities generally accumulate tax-deferred until distributions occur.
When distributed, taxable annuity earnings are generally subject to ordinary income tax.
Certain annuities also offer lifetime income arrangements that a conventional CD does not inherently provide.
Which Product Is Better?
There is no universal answer.
A short-term savings need may call for different considerations than a long-term retirement income objective.
Product selection should consider liquidity, guarantees, tax circumstances, available financial resources, and the terms of each offering.
At Doctor for Financial Health, we encourage consumers to compare the entire product—not simply two advertised rates.
A meaningful comparison starts with understanding what you’re purchasing, what protection applies, and when you can access your money.
Continue Learning
Explore Annuities vs. Other Retirement Options and Fixed Annuities.
Educational information only. Product terms, insurance protection, and tax treatment depend on individual circumstances.